Q3 ended on a weak note as rising bond yields weighed on asset class returns in September. However, for the full quarter, global equities still posted modest positive returns despite the slump in fixed income markets and rise in oil prices.
- While developed market equities returned 1.8% for the quarter, emerging market equities returned -2.9% after failing to recover from a sharp sell-off in semiconductor stocks in July. Muted returns in Q3 followed strong Q2 and year-to-date returns.
- The combination of rising oil prices, sticky inflation, and solid economic data saw a sharp rise in global bond yields, with 10-year US Treasury yields reaching 5.3%, the highest level in nearly 20 years. The Fed hiked 25 bps and signaled at least 1 more hike in 2026.
- Real assets were mixed in Q3, with rate-sensitive REITs hit hard. Commodities and natural resource equities still managed double-digit returns, thanks to the rebound in energy prices, with Brent oil rising back above $100. Although gold posted positive returns for the quarter, it was hit in September by rising rates.
- The USD was flat for the quarter, but it jumped back to life in September aided by rising oil and Fed rate hike expectations. The JPY also jumped on the back of FX interventions and BOJ rate hikes.
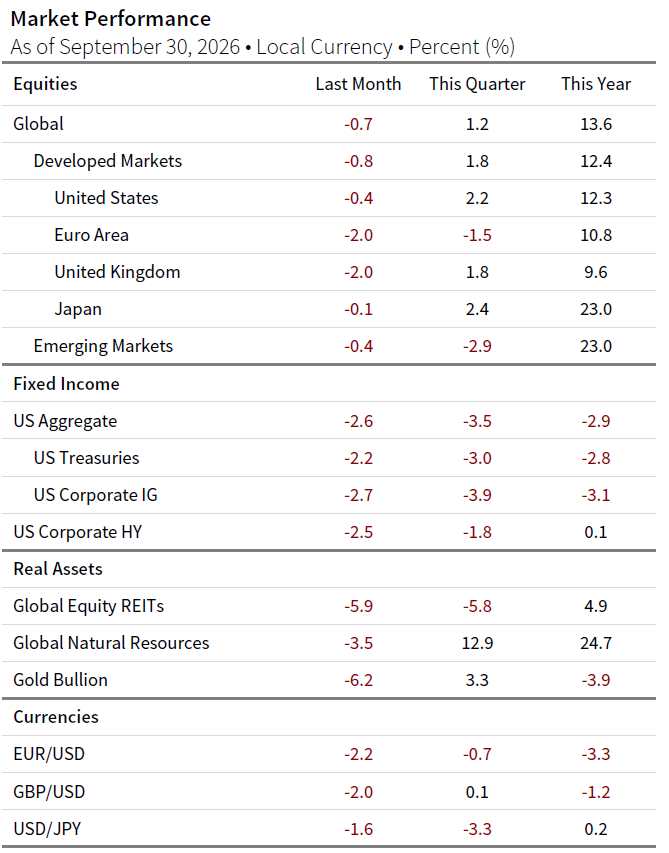
Sources: Bloomberg Index Services Limited, ICE Benchmark Administration, MSCI Inc., and Thomson Reuters Datastream. MSCI data provided “as is” without any express or implied warranties.
Notes: This edition was prepared on October 02, 2026, and it reviews developments of the prior quarter. The equity data are total returns net of dividend taxes of MSCI indexes in local currency. Global natural resources equities are represented by the MSCI All Country World Commodity Producers Index. The fixed income data are total returns for Bloomberg indexes. Gold Bullion uses the LBMA gold price. Currency performance is based on Reuters data.