Global equities rose last week as bond yields and oil prices held steady after rising in recent weeks, offering some relief from concerns over borrowing and energy costs. Euro-area stocks lagged amid fiscal concerns, while technology shares were volatile but ended the week little changed.
- Rate-sensitive sectors outperformed as bond yields stabilized, with real estate, utilities, and consumer discretionary stocks outperforming. The tech sector was little changed, despite volatility following mixed reports that raised questions about OpenAI’s revenue outlook.
- The US ten-year Treasury yield fell 6 basis points, interrupting its recent rise but remaining near a multidecade high. Brent crude held in a $100–$104-per-barrel range amid reports of improved supply prospects and renewed regional attacks. Strong Treasury auctions also helped steady bond markets.
- Euro-area equities fell 1.1%. Reports of fiscal-discipline plans from candidates ahead of France’s 2027 election helped stabilize bond yields, but fiscal risks and political uncertainty continued to weigh on stocks.
- Emerging markets equities slipped 0.2%, despite a 7% gain in Latin America. Flávio Bolsonaro drew a larger-than-expected share of the vote in Brazil’s first-round election, a result welcomed by investors who view him as the more market-friendly candidate.
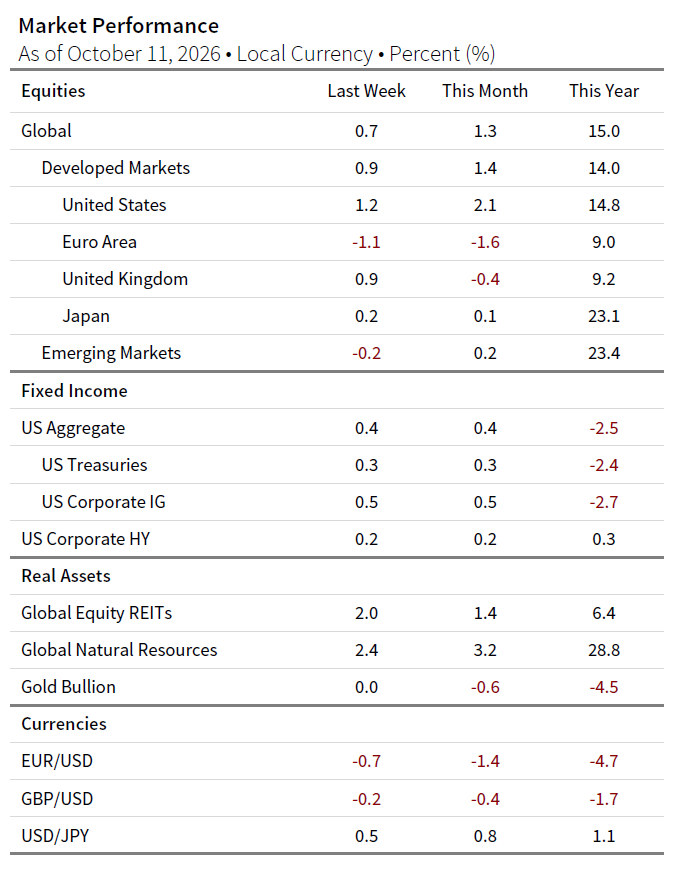
Sources: Bloomberg Index Services Limited, MSCI Inc., and Thomson Reuters Datastream. MSCI data provided “as is” without any express or implied warranties.
Notes: This edition was prepared on October 11, 2026, and it reviews developments of the prior month. The equity data are total returns net of dividend taxes of MSCI indexes in local currency. Global natural resources equities are represented by the MSCI All Country World Commodity Producers Index. The fixed income data are total returns for Bloomberg indexes. Gold Bullion uses near-month gold futures contracts, as traded on the COMEX, to determine performance. Currency performance is based on Reuters data.